Fix the REAL cause of your cash flow stress…
Painful, sleep-destroying SME cash flow shortages are very often a symptom of the systemic Cash Gaps that operate in many industries today. While “management” and “discipline” can reduce short-term symptoms, they do NOT fix the underlying root cause.
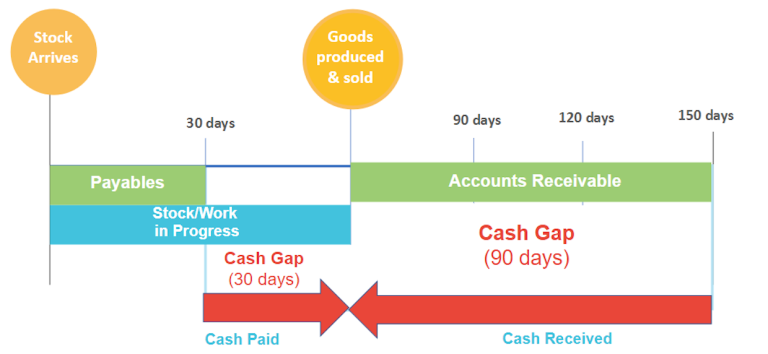
The underlying cause of painful, recurring cash flow stress in many smaller businesses is the 30/60/90 day gap between when you pay for inputs and when you get paid.
The long-term solution to a structural industry Cash Gap isn’t “working harder”. The solution is a solid Working Capital Strategy that combines expert analysis, effective business processes and high-productivity Cash Flow Tools to optimise your financial liquidity.
How big is YOUR business Cash Gap?
Does your business experience ongoing stressful Cash Gaps?
Do you spend endless hours on the phone trying to get paid?
Do you constantly shuffle bills and scrimp on resources?
Do you struggle to find cash to invest in core business efficiency?
Is your personal property at risk if your business gets into trouble?
If these are regular pain points in your business, then it’s time to review your Working Capital Strategy…
What does a practical Working Capital Strategy look like?
A sound Working Capital Strategy is a combination of:
Your Working Capital Strategy should be an ongoing process – not a one-time document – because your business will grow and change. Like any strategic planning process, it needs regular monitoring.
Key practical financing tools can reduce Cash Flow Stress
A key element of any efficient 21st century Working Capital is the careful selection of relevant, quality, tech-enabled Cash Flow Financing Tools – tools that enable your business to minimise its cash gap and maximise its financial productivity.
4 KEY CASH FLOW FINANCING TOOL SETS THAT INCREASE SME LIQUIDITY
Today’s top cash flow financing tools – when carefully implemented as part of an ongoing Working Capital Strategy – enable smart small business operators to maximise the funds available in their business. They fall into four key tool sets.

Are you tired of constantly chasing customer invoices?
Are you sick of endlessly cutting back on vital expenditure to patch over stressful cash flow gaps?
Then it could be time to book your FREE Working Capital Strategy Review – and find out what today’s top tools could do to maximise your business productivity.
TALK TO A WORKING
CAPITAL STRATEGIST
THE COSTS OF THE CASH TRAP ARE HEAVY AND CUMULATIVE
If you don’t have sufficient working capital in your business, then you can end up:
NO AMOUNT OF “BETTER CASH MANAGEMENT” CAN FIX AN INDUSTRY’S STRUCTURAL CASH GAP
All the administrative best practice in the world can’t change the impact of “baked-in” credit terms with long payment periods – 30/60/90 days – even if all your customers paid perfectly on time.
Long credit terms will still have you waiting weeks – and even months – for a big customer to pay a big invoice. During that time, payroll still has to be made, the ATO wants their due, and your suppliers have to be paid to buy materials for your next job.
Even good businesses that show excellent profits at the end of the financial year can operate in an environment of recurrent, stressful, productivity-killing periods of cash flow drought.
Is Your Business Stuck in a Cash Trap?
Talk to Martin about how you can get back in the drivers seat
WHICH MODERN FINANCE PRODUCTS SHOULD YOU CHOOSE?
None!If someone tells you straight up that “XYZ product” is THE ANSWER – run!! (Especially if they go on to talk about toxic Fast Cash Flow Loans!)
No one can tell you the “right” product for your needs until AFTER they’ve done a Working Capital Analysis of how cash flows through your business AND delivered a Working Capital Strategy that’s designed for your business (not your cousin’s brother’s wife’s micro-business).
It doesn’t have to be a long document or a time-consuming process – but it does have to be based on your business, your goals, your customers and your supply chain.
Martin Cattach is an expert Working Capital Strategist
Over more than 15 years in the business finance field, Martin has analysed the finances of thousands of businesses.
His decades of experience in the finance industry, Information Technology – AND in small business – uniquely equip him to assist SME businesses to select and implement the best finance solutions for their needs.
Martin will quickly built a Working Capital Cash Flow plan that will take the financial stress out of your business operations and free up the funds you need to grow your business impact.