How to get your business finances match-fit for FY2026/27
The 2020s have been a tough decade so far – full of global and local disruptions.
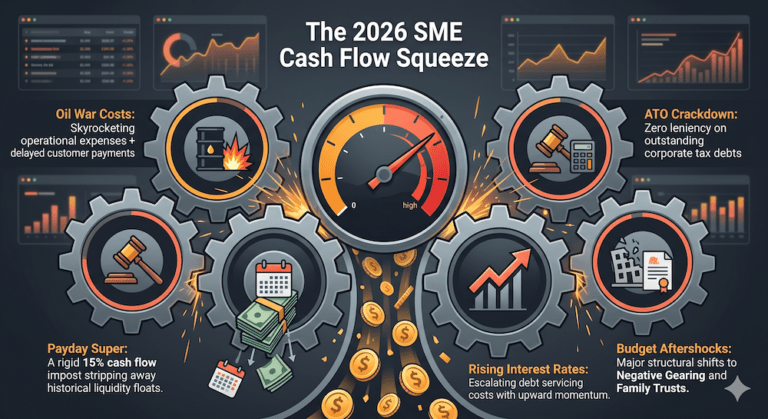
Internationally, we started the decade with a supply-chain-disrupting plague, then moved onto tariff disruptions and multiple wars. In Australia, we’re dealing with a backlog of COVID-induced tax debt, interest rate rises, major taxation system changes PLUS the looming compliance challenges of Payday Super.
Many businesses that have soldiered on bravely through the first five years of this decade using “everybody knows” thinking are starting to hit their limits – and it’s showing up in today’s late payment and insolvency statistics.
In a May CreditWise webinar I attended, their collections experts reported that:
- ASIC-required external administrations sat at record highs through 2025
- Growth has gone flat, with average estimated turnover growth across their customer base hovering around 1% for the last six quarters
- Overdue payment rates on outstanding Debtors are increasing, particularly in construction.
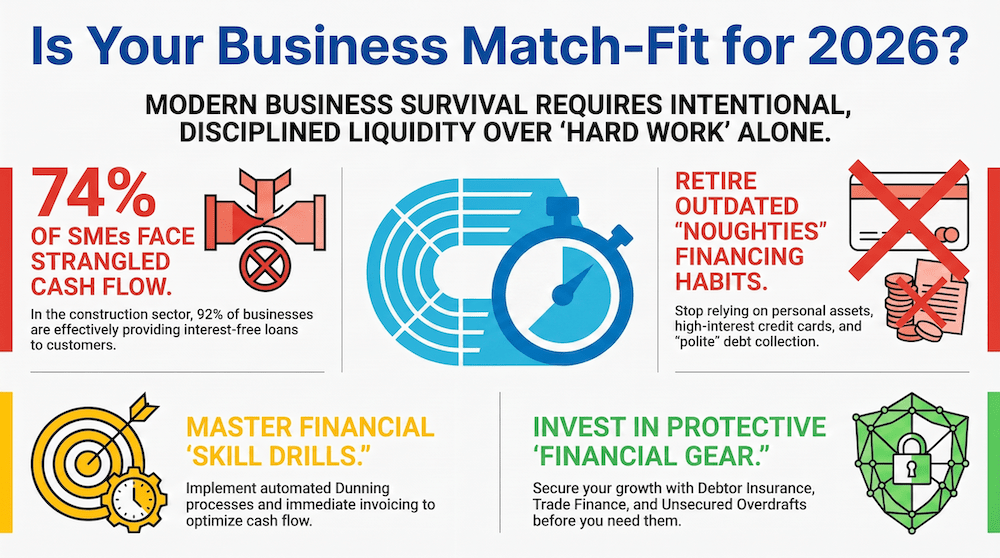
74% of Australian small businesses have overdue invoices strangling their cash flow. In construction, that number rockets to a massive 92% of businesses giving interest-free loans to their customers. Yet it’s almost terrifying how few SMEs have a professional collections process, let alone Debtor Insurance.
It IS tough – absolutely – so what can you DO?
In this environment, it’s time for every business to take a serious look at whether their business financing strategies and practices are “match fit” for the third decade of the twenty-first century.
Tennis players don’t play their matches in Dunlop Volleys anymore. Their rackets are made of carbon fibre, not wood. They do warm-ups and cool downs and stay hydrated – scientifically. They train extensively to stay fit in the face of gruelling competition schedules.
The times have changed; information and business technologies have changed. Yet a lot of small businesses are still running “noughties” financing strategies such as:
- Bank loans secured by personal assets.
- High-interest credit cards.
- Top-ups from “the bank of family and friends”.
- Work super hard and “rob Peter to pay Paul” every payday.
- Collect debts by “waiting politely and then making pleading phone calls”
Is your business financing STRATEGY “match fit” for today’s reality?
To thrive and grow sustainably in today’s business environment, you need an intentional, disciplined Working Capital Strategy that maximises your business liquidity (fitness).
If you’re serious about minimising your risks of career-ending injury while playing sport, then you don’t just show up on the day – you prepare (and prepare and prepare and prepare). You work on multiple fronts:
- You build muscle strength – particularly core strength.
- You work to increase your functional flexibility.
- You invest in the right protective equipment – from helmets to shin guards.
- You build your cardio fitness, so your body can carry oxygen to your muscles.
- You do skill drills to build specific capabilities.
You don’t just succeed in sport today with “hard work and perseverance” – you use modern training techniques, you invest in good tools and equipment, and you team up with experts whose knowledge enables you to get better results and minimise injury risks.
Getting business-fit financially in 2026
This fitness approach should apply to your business financing and administration as you prepare for whatever FY2026-27 has in store for us:
- Skill and fitness drills: Strong business processes – making sure that you have financial disciplines like Dunning Processes and Immediate Invoicing in place to optimise your cash flow.
- Flexibility: You make sure you have the financial flexibility you need to take on new opportunities. For example, by putting smart tools like Unsecured Overdrafts in place before you need them. Also evaluate smart, liquidity-increasing tools like LucaPLUS and ARCHA Finance Team Credit Cards
- Protective and enabling gear: Such as Debtor Insurance – which you can get at affordable wholesale rates when you access Debtor Finance (particularly useful in high-risk industries like construction).
- Cardio fitness: Good processes that enable freely flowing cash using Debtor Finance and Trade Finance – ready to carry you forward into the future. You also make sure you’re using deposits and pre-payments to prevent peaks and troughs.
Is your business ready to thrive and grow?
It’s time to start treating disruption as the new normal. It’s time to make sure that your business processes and strategies are professional, robust and match-fit – so that you’re resilient in the face of whatever comes next.
Don’t keep playing in Dunlop Volleys using a wooden racket because they’re “good enough” or “they’ve worked so far”.
If you’re not sure what a financially fit business process looks like today, then you can download my 26-point Cash Flow Maximisation Checklist.
If you’re ready to level up your business cash flow in FY 2026-27, but aren’t sure where to start, then book a free Virtual Coffee today to find out how Martin can help your business thrive.